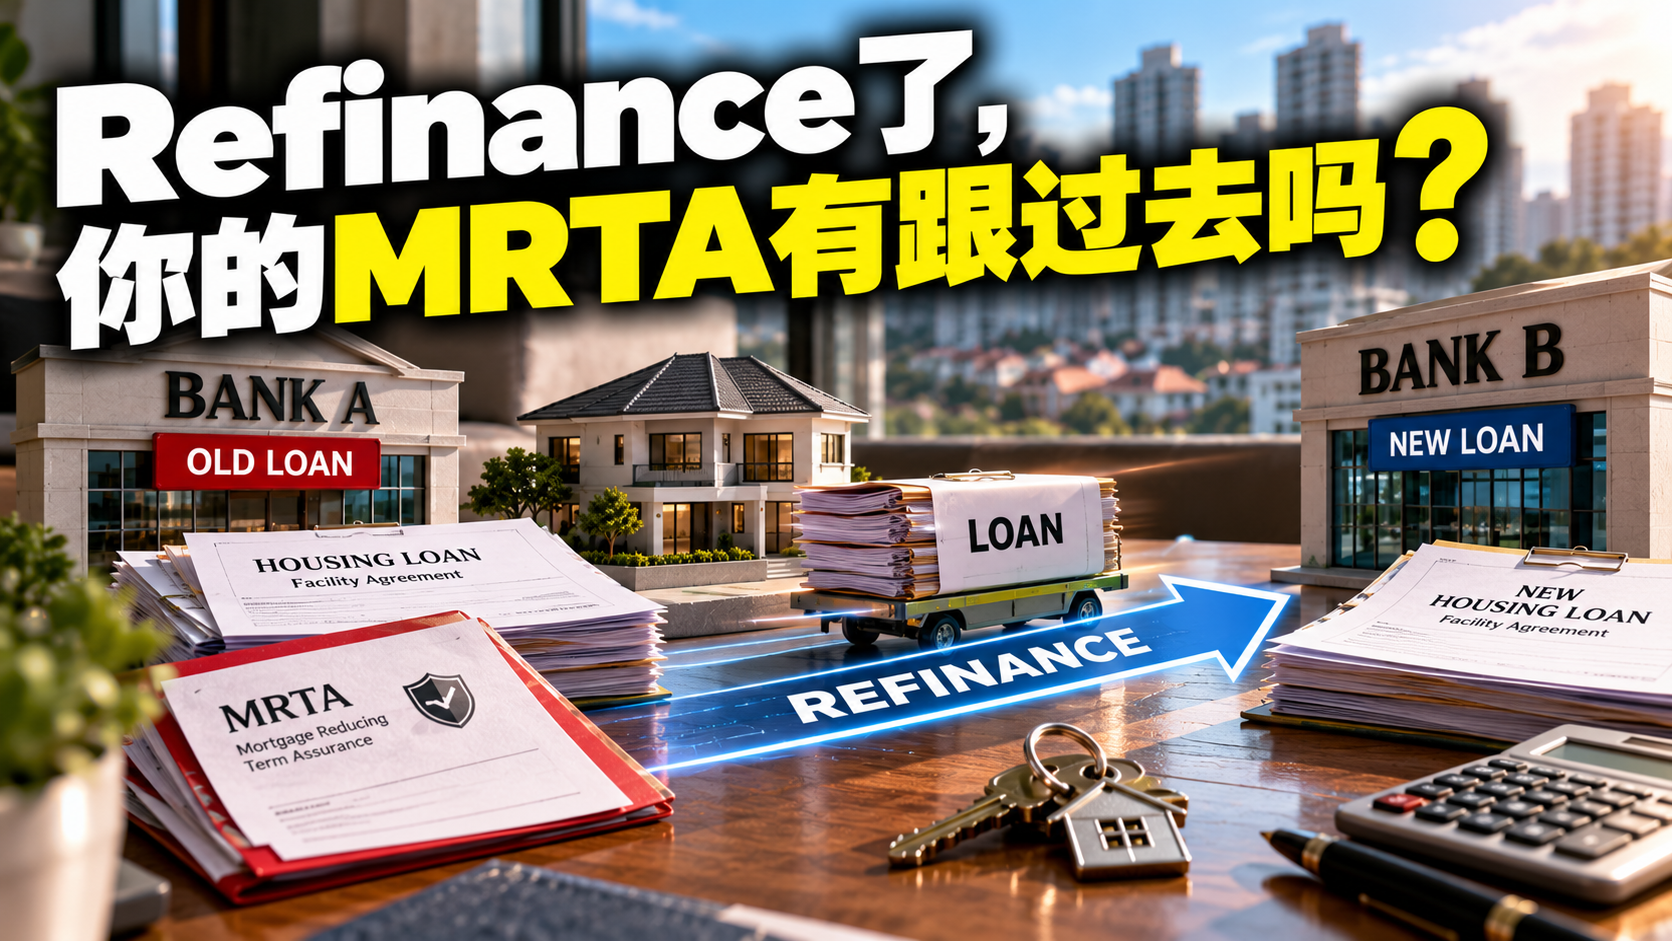
卖屋 / Refinance了,原本买的MRTA、MLTA怎么办?
Loan可以settle、换bank、缩短甚至重新拉长,但当年买的mortgage protection不会自动知道你做了什么。卖屋或refinance之前,旧Certificate一定要重新打开。
30 秒先讲懂
换 Loan ≠ Protection 自动搬家。Sell、early settlement、refinance、advance payment、tenure change 都不是同一件事;旧 protection 的 surrender、continuation、refund 或 portability 要看具体产品条款。
不要等旧 Loan settle 完才想起 protection。
① Old Loan Settlement
旧 facility 到底怎样结清、日期是什么。
② Old Protection Certificate
当年到底买什么、term 到哪里、谁被保。
③ Surrender / Continuation Terms
有没有相关 option、怎样处理,直接看产品条款,不靠“朋友以前拿到 refund”。
④ New Loan + New Protection
Bank B 新 facility 需要怎样安排 protection,重新确认,不假设旧 protection 自动覆盖。
为什么 refinance 后重新申请 protection,条件也可能变?
因为今天的你不是 5 年前的你。Age、health、sum assured、term、underwriting 与新 facility 都可能不同。
“我供了 8 年,剩 27 年,所以应该退 27/35 的 premium?”
这个 calculation 很顺脑,但不能这样算。
问题:Surrender / refund 并不是简单把 unused years 按比例倒算。有没有 surrender value、怎样计算、facility settle 后能不能 continue,都要看具体 product terms。
Refinance 最简单的理解:Loan 搬家了,Protection 不会自己收到通知搬过去。
最危险的想法是:“我以前已经有 MRTA,所以 Bank B 这笔 RM560k 应该自动继续 cover。”
不能这样假设。旧 protection 是按当时的 Certificate / facility arrangement 建立;新 Loan 是另一笔 facility。

📚 Sources + Fact Boundary
- Maybank / Etiqa — current MRTA early-settlement / surrender information (product-specific)
- Sun Life / CIMB — current mortgage protection materials
- Actual Certificate / Master Policy — continuation / surrender mechanics are product-specific
最后 Fact Recheck:2026年10月5日。 Mortgage protection 的 commencement、TPD、sum assured、surrender、continuation、payee / assignment 等均可能因 Bank、Insurer、Certificate / PDS 而不同。本文用于帮助买家看懂结构,不构成保险、法律或遗产分配意见。
看不懂你的 Loan + Protection?
我准备 Sell / Refinance,想先搞懂旧 MRTA / MLTA 怎么处理。把你现在卡住的问题告诉 Alan,先搞懂结构,再决定下一步。
💬 WhatsApp Alan 问清楚